Trump's $1.4 Billion Crypto Haul Sinks the Senate's Crypto Bill
The Clarity Act's ethics provisions leave plenty of room for the president to keep profiting, and its regulatory framework hands bureaucrats too much discretion.
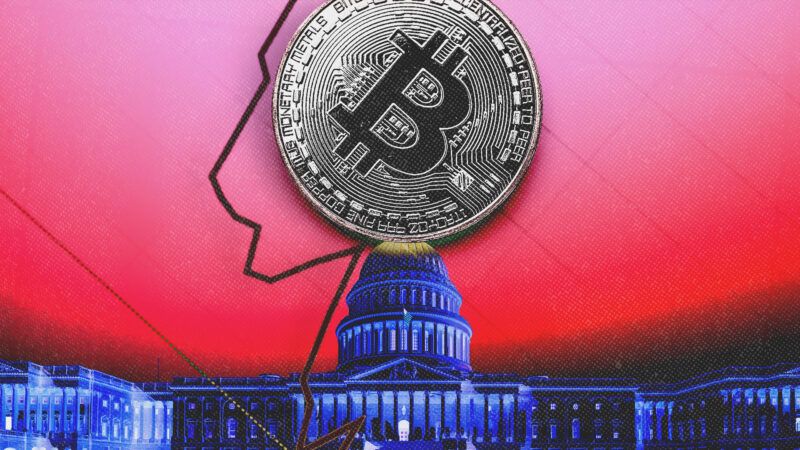
A failed Senate procedural vote on the Digital Asset Market Clarity Act on Tuesday may have saved crypto consumers from a questionable regulatory bill backed by industry insiders.
The bill—a first-of-its-kind regulatory framework for the crypto industry—would have drawn clear jurisdictional lines between the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC) on regulating the offer and sale of digital commodities.
Instead of the SEC regulating crypto through individual enforcement—which it currently does—the bill would give Americans holding digital assets a pathway to legal certainty by establishing disclosure requirements, preserving both agencies' anti-fraud authorities and creating risk-management, cybersecurity, and compliance standards for decentralized finance.
Still, the bill also gives federal agencies far too much discretion, authorizing them to set new regulations and exemptions and coordinate with international regulators if it is "in the public interest or for the protection of investors," an invitation for career bureaucrats to decide what's best for Americans.
After a year of bipartisan negotiations, The Wall Street Journal reports the bill failed to pass a procedural vote—which would have allowed it to be fully voted on by the Senate—because Democrats weren't sold on the bill's ethics provisions as strong enough to prevent President Donald Trump "from continuing to profit off digital assets."
It's a statement that seems to ring true, considering an ABC News report that Trump's June financial disclosure reports showed crypto earnings of more than $1.4 billion. This includes more than $591 million from World Liberty Financial (WLF), $636 million from his meme coin business CIC Digital, and more than $196 million from the equity sale of a holding company linked to WLF. Last year, the president announced that he would hold an "intimate private dinner" for the top 220 holders of his $TRUMP meme coin. In the days after the announcement, the coin's value surged by 50 percent.
The bill would bar the president, vice president, members of Congress, senior federal officials, and their spouses from profiting from crypto tokens, promoting tokens, or owning a meaningful stake ($15,000 or more) in a crypto venture such as WLF. Anyone who currently owns a stake would have to sell it or place it in a blind trust—or face fines of at least $500,000 and the potential loss of any profits.
These provisions are a step in the right direction, but they're largely milquetoast and do little to address the air of corruption surrounding the president's crypto dealings.
With a blind trust, the president could still profit from WLF, and any new tokens the company launches would be grandfathered in under the bill. The ethics provisions also fail to account for children and other relatives. That would seemingly insulate WLF, which was launched by Trump's sons and the sons of U.S. peace envoy Steve Witkoff. The bill tasks the Department of Justice (DOJ) with enforcing penalties against violators. Given what we've seen from the department under Trump, it's fair to wonder whether the attorney general would remain impartial.
The bill's enforcement mechanism gives state attorneys general the power to sue the Justice Department for any harm to a state or its residents. However, it does not allow them to sue federal officials. State AGs are also empowered to hold trading platforms that run afoul of state laws accountable.
Despite the disagreements, the bill is still on the Senate calendar and could resurface. On Tuesday, Sen. Thom Tillis (R–N.C.) said this is "not the end" for the bill. It might be wishful thinking from Tillis; Forbes reports that it's "unlikely Senate Majority Leader John Thune will allocate calendar time without certainty that they have enough Republican and Democratic commitments."
Lawmakers' back-and-forth hasn't stopped the push to regulate the crypto industry.
On Thursday, in the absence of congressional leadership, the SEC issued an order—part of the agency's Project Crypto initiative to make America the center of the crypto industry—allowing certain trading platforms to issue digital tokens that represent publicly traded U.S. stocks. The order grants a five-year Innovation Exemption to platforms that facilitate tokenized stock trading and further integrates digital assets with traditional markets like Nasdaq and the New York Stock Exchange.
In a statement on X, CFTC Chairman Mike Selig called the failed vote on the bill "unfortunate," adding that the CFTC is "locked in and ready to ship its rules for the new frontier of finance."