Treasury Backs Down on Biden-Era Cryptocurrency Surveillance Proposal
It’s a small victory for financial privacy against escalating surveillance.
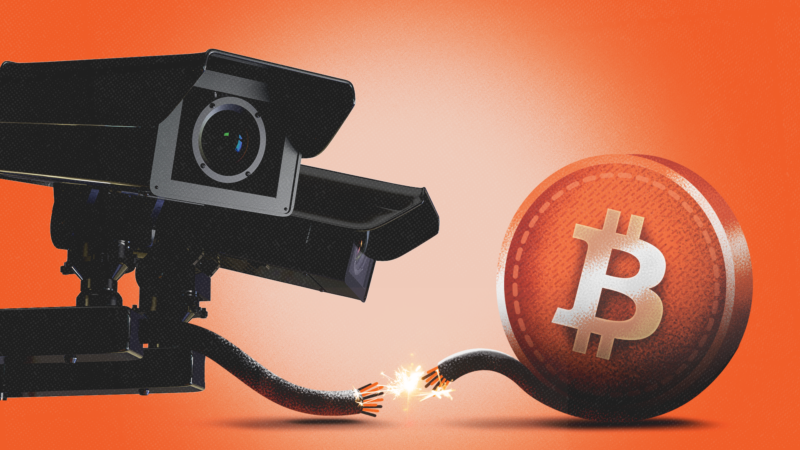
The U.S. Treasury's Financial Crimes Enforcement Network (FinCEN) has withdrawn its proposal for a rule that would require financial institutions to report on cryptocurrency transactions that they "know, suspect, or have reason to suspect" involve mixing in a foreign jurisdiction. The proposal was first made in October 2023, and the government withdrew it this week, citing complaints from the crypto industry and privacy concerns.
"While FinCEN maintains that illicit actors continue to use mixers and other tools and methods to hinder law enforcement investigations, this withdrawal is informed by the concerns from commenters that the expansive definition of [Convertible Virtual Currency] mixing in the proposed rule could have a chilling effect on legitimate activity and place a large reporting burden on covered financial institutions," the withdrawal announcement states.
The USA PATRIOT Act of 2001 gives the Treasury the authority to force banks and other institutions to report on their own customers for national security reasons. Originally created for counterterrorism, this surveillance has steadily expanded into the American and international financial system. The Trump administration has tried to use FinCEN to find illegal immigration and has set up secretive "predictive intelligence" units at the Department of Homeland Security that look at Americans' financial activity, among other data. But in the case of cryptocurrency, the administration has a pro-privacy policy.
In a July 2025 report, cited by the recent FinCEN announcement, the White House argued that excessive reporting rules might make American crypto businesses less competitive, and that "lawful users of digital assets may leverage mixers to enable financial privacy when transacting through public blockchains." President Donald Trump and his family have been particularly enthusiastic investors in cryptocurrency, and critics accuse them of a conflict of interest.
Most crypto transactions take place on a public "blockchain" ledger. A "mixer," also known as a "tumbler," is a service that pools together multiple cryptocurrency transactions so that it is difficult to match senders and receivers. For example, if Alice wants to send Bob some bitcoin, she might send it through a mixer, which also processes transactions between Carol and Dan and between Charlie and David. From the perspective of someone looking at the blockchain, the money that Alice sent could have gone to Bob, Dan, or David, and the money that Bob received might have come from Alice, Carol, or Charlie.
FinCEN first mentioned mixers in a 2019 guidance document insisting that "a money transmitter cannot avoid its regulatory obligations because it chooses to provide money transmission services using anonymity-enhanced CVC," though it didn't "establish any new regulatory expectations or requirements." The Treasury's Office of Foreign Assets Control shut down two mixers in 2022 for allegedly helping launder money stolen by North Korean hackers. A federal court overturned the sanctions on one mixer, Tornado Cash, in 2024.
The Biden administration declared mixers a "primary money laundering concern" and proposed the new FinCEN reporting rules in October 2023. Much of the administration's messaging focused on the recent Hamas attacks against Israel as the reason for the rule. "The Treasury Department is aggressively combating illicit use of all aspects of the CVC ecosystem by terrorist groups, including Hamas and Palestinian Islamic Jihad," Deputy Treasury Secretary Wally Adeyemo told reporters at the time. But the actual FinCEN proposal focused on North Korean and Russian cybercrimes and explicitly said that a "narrow approach" focusing on Hamas or other terrorist groups "would be insufficient to address the relevant risks."
The cryptocurrency industry hit back. The Blockchain Association, an industry association, argued that there is "nothing inherently suspicious about desiring the same degree of privacy available for traditional financial transactions" and that the rules could "drive illicit digital asset transactions abroad where they may be subject to reduced or no regulatory oversight." Coinbase, the largest American crypto exchange, predicted that the new FinCEN rule will "just lead to bulk reporting of non-suspicious transactions." Several other exchanges complained that the rule would discourage "good cybersecurity practices."
The White House echoed these industry complaints in its July 2025 report, and the Treasury finally got the message. Still, the Treasury's withdrawal announcement hinted that it hasn't given up entirely on regulating mixers. "FinCEN will continue to monitor activity involving CVC mixers for indicia of money laundering, terrorist financing, or other illicit finance activity, and may take appropriate steps in the future to mitigate any such activity," it states.